BTL Property Finance Options for Renovations before Letting
This article explores finance for an unlettable property, including bridging finance, refurbishment lending and refinancing once works are complete.
04/11/2026By Sunil Chander · Co-Founder
This article explores finance for an unlettable property, including bridging finance, refurbishment lending and refinancing once works are complete.
An "unlettable" buy-to-let (BTL) property will often need substantial work before it can be occupied and become acceptable to a mainstream BTL mortgage lender. Landlords who take on such a property may therefore need short-term property condition improvement finance to complete the work before moving on to a conventional buy-to-let mortgage. This article explores finance options for an unlettable property, including bridging finance, refurbishment lending and refinancing once works are complete.
What makes a buy-to-let property unlettable?
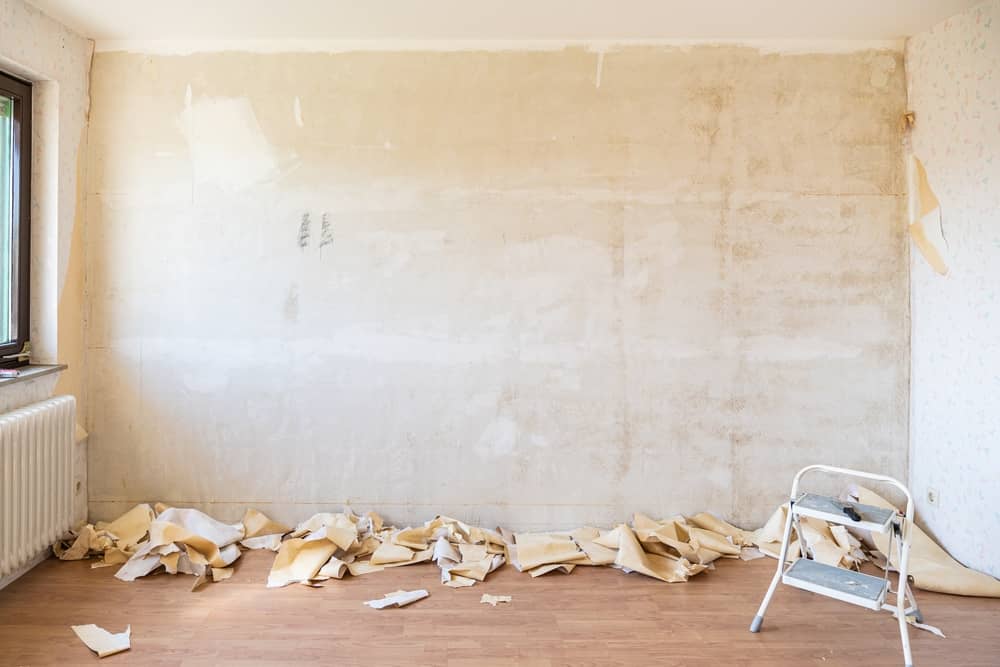
An unlettable property cannot safely or practically be occupied in its present condition. Common lender concerns include a missing or unusable kitchen or bathroom, an insecure building, serious structural defects, inadequate heating, or a roof that is not watertight. These conditions can make the property unacceptable as security because it may be difficult to occupy or resell.
Health and safety problems can create a separate barrier to letting. The Housing Health and Safety Rating System is used by local authorities in England and Wales to assess residential hazards. Where a Category 1 hazard exists, which is the most severe, the local authority must take appropriate enforcement action under the Housing Act 2004. Enforcement may include an improvement notice, prohibition order or emergency action. From 22 June 2026, English local authorities can also impose a civil penalty of up to £7,000 where the statutory conditions are met and a landlord has failed to take reasonably practicable steps to address a Category 1 hazard.
Why mainstream lenders may reject the property
Mainstream mortgage lenders may decline an uninhabitable property because the security does not satisfy their condition, valuation or insurance requirements. The issue is not simply that the property has no current tenant. Buy-to-let affordability may be assessed using the rent the property is expected to achieve, but the building must still meet the lender's minimum standards before a standard mortgage can be completed. A property without essential facilities or structural integrity presents a higher resale risk. A building that cannot readily be occupied or mortgaged may also attract fewer buyers, so conventional funding is often unavailable until repairs are complete.
Bridging finance to renovate before renting
Bridging finance is a common route for landlords who need to renovate before renting. This is short-term secured borrowing intended to be repaid through a defined exit, usually the sale of the property or refinancing once the work is complete. A bridging lender will consider the property's current condition and value, the proposed works, future value and exit strategy. This can make bridging suitable for properties that standard mortgage lenders will not yet accept. The landlord can complete the work and then refinance onto a buy-to-let mortgage supported by an acceptable valuation and expected market rent. Bridging finance normally costs more than long-term mortgage borrowing. A realistic works budget, including contingency, and timetable and repayment plan are essential.
Landlord refurbishment loans and buy to let refurb funding
A landlord refurbishment loan is often a form of bridging finance structured around renovation work. The terms renovation loan, refurbishment bridging loan and refurbishment finance are frequently used for overlapping products rather than entirely separate categories of lending. The financing structure depends on the lender and the scale of the work. Some facilities provide the agreed borrowing upfront, while others release parts of the works budget in stages as the project progresses. Staged funding may require inspections before each drawdown. Landlords should confirm how interest and maximum advance are calculated.
When property development finance may be more appropriate
Property development finance may be more appropriate where the project involves construction risk beyond an ordinary refurbishment. This can include a ground-up build, substantial conversion, major structural redevelopment or a scheme that creates additional units. A single property is not automatically unsuitable for development finance; the nature and complexity of the work are more important than the number of properties involved. For lighter work, refurbishment bridging may offer a simpler route. The boundary between the products can also be lender-specific.
Can home improvement loans fund a rental renovation?
Home improvement loans may fund modest work, but many are unsecured consumer products designed around personal borrowing rather than a commercial property project. Their loan limits, terms and eligibility may make them unsuitable for major buy to let refurb funding. A landlord must also check that the lender permits the money to be used for a rental property or business purpose. Where the property is already mortgageable, and the work is limited, an unsecured loan, further advance or remortgage may be possible. These routes should not be assumed to work where the property is materially uninhabitable.
Insurance and preparation before applying
Standard landlord policies often restrict cover after a property has been vacant for a specified period or while substantial work is underway. The landlord may need unoccupied or renovation cover, or an approved extension to an existing policy. Before approaching a lender, the landlord should prepare an itemised schedule of works, contractor estimates, a realistic programme, evidence of funds and a clear exit strategy. Relevant permissions, approvals and specialist reports should also be available.
Conclusion
Finance for an unlettable property is usually designed to bridge the period between acquisition and the point at which the property becomes mortgageable and lettable. Bridging finance and refurbishment bridging are the main short-term routes, while property development finance may suit more complex structural projects. The right choice depends on the property's condition, work required, total funding structure and repayment plan.
FAQs
Q. What counts as an unlettable buy-to-let property?
A. An unlettable property cannot safely or practically be occupied in its current condition. It may lack a working kitchen or bathroom, have an insecure structure or a roof that is not watertight, require major repairs, or contain serious health and safety hazards. Individual mortgage lenders apply their own minimum property standards.
Q. Does a Category 1 Housing Health and Safety Rating System hazard automatically make letting illegal?
A. A Category 1 Housing Health and Safety Rating System hazard does not create an automatic blanket prohibition in every case. It requires the local authority to take appropriate enforcement action, which may include requiring repairs or prohibiting the use of part or all of the property. Separate fitness, repair and safety duties may also prevent safe occupation until the problem is resolved.
Q. Why might a mainstream mortgage lender reject an uninhabitable property?
A. The lender may reject it because the building fails its security, valuation or insurance requirements. Although expected market rent can be considered for buy-to-let affordability, the property must still meet the lender's minimum condition standards.
Q. How does bridging finance help landlords renovate before renting?
A. Bridging finance provides short-term secured funding while repairs are completed. The loan is normally repaid by refinancing onto a longer-term mortgage once the property is acceptable to that lender or through a sale.
Q. Is a landlord refurbishment loan different from bridging finance?
A. A landlord refurbishment loan is often a type of bridging finance intended for renovation work. Some lenders provide the facility upfront, while others release the works budget in stages. Product names and structures vary between lenders.
Q. How quickly can bridging finance be arranged?
A. Bridging finance can sometimes complete faster than a standard mortgage, but no fixed timescale applies. Valuation, legal work, title issues, and the lender's due diligence and complexity of the renovation can all affect completion.
Q. How much deposit or equity is needed?
A. The required contribution depends on the valuation basis, property condition, project costs, borrower experience and exit strategy. A current lender quotation is needed for a reliable figure.
Q. When is property development finance more suitable?
A. Property development finance may be more suitable for a new build, substantial conversion, major structural redevelopment or a project creating additional units. The scale and construction risk matter more than whether the scheme contains one property or several.
Q. Can home improvement loans be used for buy to let refurb funding?
A. They may be useful for limited work if the lender permits business or rental-property use. Many home improvement loans are unsecured consumer products with borrowing limits or terms that do not suit a major landlord renovation.
Q. What should a landlord prepare before applying?
A. A lender will usually need a clear exit strategy, valuation information, an itemised works schedule, contractor costs, a project timetable, and evidence that the borrower can cover deposits, fees, contingencies, and any cost overruns. Relevant planning, building control, and insurance documents may also be required.
About the author
Sunil Chander
Co-Founder
Sunil oversees operations and compliance at Pauzible, drawing on his extensive experience as the founder and CEO of Dawnbud Limited, a financial services consulting firm. His prior career included senior roles in investment banking at Smith New Court and NatWest. He holds an MBA from LBS, M Litt from Oxford and a PhD from Cambridge.