BTL Refurbishment Budget: What Landlords Should Include
This article explores what a realistic buy-to-let refurbishment budget should include to ensure landlords adequately allocate the funds required.
09/11/2026By Sunil Chander · Co-Founder
This article explores what a realistic buy-to-let refurbishment budget should include to ensure landlords adequately allocate the funds required.
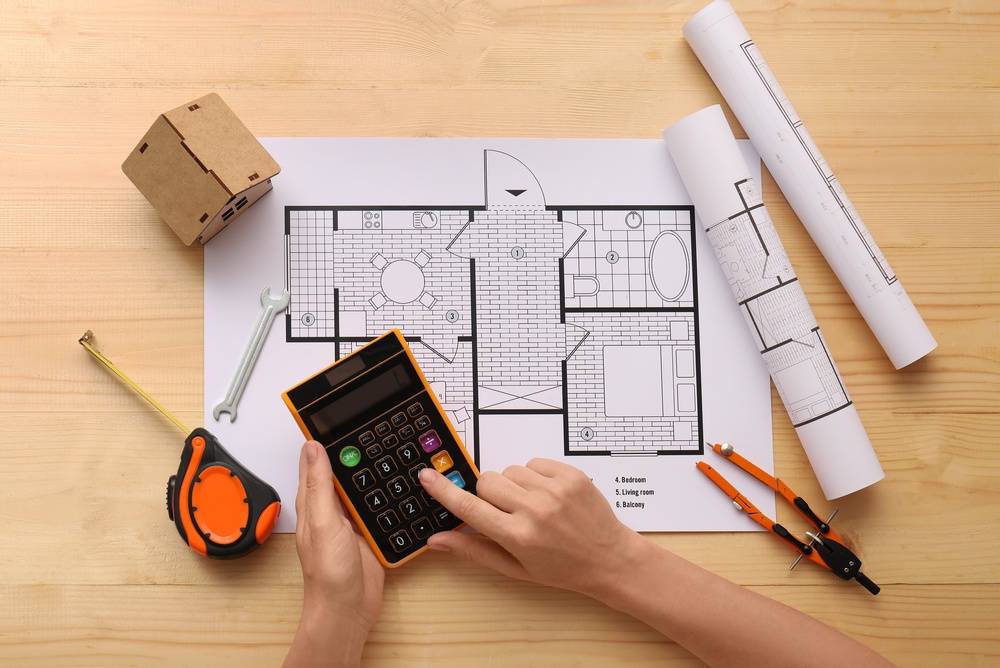
A refurbishment budget loosely built around a kitchen, a bathroom and a coat of paint rarely covers all the costs that emerge. Landlords who scope only the visible work often find themselves short once a contractor opens the floors or tests the wiring. Getting it right at the planning stage separates a refurbishment that results in a quick letting and performs well from one that drags on and erodes the return it was meant to protect. This article explores what landlords should consider when planning a realistic buy-to-let refurbishment budget.
What a realistic buy-to-let refurbishment budget should cover
Landlord renovation costs typically fall into four categories: cosmetic work, core services, structural/layout work, and compliance. Cosmetic work covers decoration, flooring and surface-level kitchen or bathroom updates. Core services include electrics, plumbing and heating, which can often be the items that turn a modest refresh into a much larger project once properly inspected. Structural and layout work may include alterations to load-bearing walls, floors, foundations or the roof structure, as well as extensions, loft conversions, and internal reconfiguration. Compliance covers certification, testing and any building control sign-off that the work requires.
A general costing overview
As a broad benchmark for a full property refurbishment, landlords can expect potentially £700 to £2,000 per square metre. This should be treated as a starting point for early budgeting rather than a fixed quote, as costs can vary significantly. Current UK cost guidance estimates that renovating a typical three-bedroom house could cost between £43,530 and £110,350, plus VAT. These are ballpark figures rather than a fixed national benchmark, and the final cost will depend on the property, location and scope of work.
Understanding rental property refurbishment costs by specification level
A useful property renovation checklist separates the budget by specification level rather than by room alone:
1. Low-spec, durable refurbishment
A low-spec, durable refurbishment retains the existing layouts of the house, uses hard-wearing finishes and prioritises preparation over decorative extras. This is often suited to rental properties where the rental yield matters more than design detail.
2. Mid-spec refurbishment
A mid-spec refurbishment balances presentation with practicality. This is aimed at ensuring the property lets well without drifting into excessive finishes that may not justify their cost in additional rent.
3. High-spec refurbishment
A high-spec refurbishment is an upgrade that utilises premium materials and advanced technology such as smart home automation. This can work in the right area and with the right tenant market, but premium finishings will not compensate for bad layout, weak ventilation or electrics. It is essential to get the basics right as the priority.
Within any refurb cost estimate, the mechanical and electrical elements usually test the budget hardest. A boiler replacement is rarely just a boiler if the pipework, radiators or flue need attention, and a rewire is seldom cabling alone once chasing, making good and certification are included. Building an allowance for these items into the initial estimate keeps the wider budget under control.
Structural and specialist works: Costing loft conversions
Where a refurbishment extends into structural work, such as a loft conversion to add a bedroom or increase rental value, the numbers can change considerably. A loft conversion cost in the UK for 2026 typically ranges from around £27,500 for a straightforward Velux conversion to £65,000 or more for a Mansard conversion, with a Dormer conversion averaging around £50,000 for a 30 square metre space.
Larger projects, such as loft conversions, should carry their own line in the budget, separate from the core refurbishment, since they typically involve a structural engineer, building control sign-off and a build programme that may range from around four to twelve weeks, depending on the conversion type, with complex projects potentially taking longer.
Contingency and the costs landlords overlook
A refurb cost estimate that does not include contingency is incomplete. Many renovation cost guides suggest allowing around 10-15% for unforeseen work. A higher allowance may be appropriate for older, heavily altered or poorly documented properties, although the contingency should ultimately reflect the risks identified during surveys and inspections.
Beyond contingency, landlords commonly under-budget for architect and structural engineer fees, planning and building control costs, skip hire, and the final decoration and snagging that gets a property genuinely ready to market. The combined cost of these items varies considerably according to the project and the professional services required, so they should be priced separately rather than absorbed into a general contingency figure. VAT is another consideration.
Additional costs to consider
Lost rent or void periods during the work
Surveys and investigations
Party wall surveyor costs where applicable
Asbestos or protected-species surveys
Temporary security, insurance and utility costs
Finance and valuation fees
Cleaning, furnishing and final compliance inspections
Funding a refurbishment budget shortfall
Landlords facing a refurbishment budget shortfall may consider several funding routes, including remortgaging, further advances, refurbishment finance, bridging finance and secured borrowing. Pauzible offers a fixed-term equity partnership that allows landlords to release funds against the equity in a buy-to-let property. The terms are offered as two-, three- or five-year arrangements, with a monthly rent share plus a separate interest cost, which can be paid monthly or deferred until the end of the term.
Landlords may be able to release up to £500,000 per property, up to 85% combined loan-to-value and subject to combined interest coverage, and financial and credit profile considerations. At the end of the term, the final repayment is either fixed upfront or linked to the property's value.
Conclusion
A buy-to-let refurbishment budget is only as reliable as the categories it accounts for. Cosmetic work is easiest to price accurately, but structural work, core services, compliance and contingency determine whether the final bill matches the original estimate. Landlords who build their budget in layers, starting with the core scope, and then a risk allowance and compliance close-out costs, are far less likely to be caught out once the work begins. If you would like to learn more about Pauzible's equity partnership model, contact our team today or use our helpful calculator to get started.
FAQs
Q. What should be included in a buy-to-let refurbishment budget?
A. A realistic budget should cover cosmetic work such as decoration and flooring, core services such as electrics and heating, any structural changes, compliance and certification costs, and a contingency allowance. Omitting one of these categories can leave a significant gap between the initial estimate and the final cost.
Q. How much does a typical rental property refurbishment cost in the UK?
A. A full refurbishment of a typical three-bedroom house sits between roughly £43,530 and £110,350, plus VAT, with a broad benchmark of £700 to £2,000 per square metre. The final figure depends heavily on the property's condition and location, and scope and specification level.
Q. How much contingency should landlords build into a refurb cost estimate?
A. Guidance generally points to a contingency allowance of 10-15% of the total project cost, and possibly higher for older or period properties. This protects the budget if and when hidden defects appear once walls, floors or services are opened up.
Q. How much does a loft conversion typically cost?
A. UK loft conversion costs typically range from around £27,500 for a Velux conversion to £65,000 or more for a Mansard conversion, with a Dormer conversion averaging around £50,000. Costs vary by conversion type, property size and location.
Q. What is the difference between low-spec, mid-spec and high-spec refurbishments?
A. A low-spec refurbishment prioritises durability and retains existing layouts; a mid-spec refurbishment balances presentation with practicality; and a high-spec refurbishment uses premium fittings and finishes. The appropriate specification depends on local tenant expectations, achievable rent, expected maintenance costs and the landlord's longer-term strategy.
Q. What costs do landlords most commonly forget to budget for?
A. Common oversights include architect and structural engineer fees, planning and building control costs, skip hire, and final decoration and snagging.
Q. Should electrics and plumbing be inspected before setting a refurbishment budget?
A. Yes. Core services are frequently where budgets are tested most, since a boiler or wiring issue can turn a modest refresh into a much larger project. An inspection before finalising the budget reduces the risk of costly surprises once work begins.
Q. Does a loft conversion always require planning permission?
A. Many loft conversions fall under permitted development and do not require full planning permission, though this depends on the size, design and location of the property. Building regulations approval is required regardless of whether planning permission is needed.
Q. Why should landlords use a property renovation checklist?
A. A property renovation checklist breaks a refurbishment down by specification level and cost category rather than by room alone, making it easier to see where a budget is likely to be tested.
Q. How can landlords use Pauzible to fund a refurbishment budget shortfall?
A. Pauzible's equity partnership enables landlords to release funds against the equity in a buy-to-let property through a two-, three- or five-year arrangement, involving paying a monthly rent share plus a separate interest cost that can be paid monthly or deferred to the end of the term.
About the author
Sunil Chander
Co-Founder
Sunil oversees operations and compliance at Pauzible, drawing on his extensive experience as the founder and CEO of Dawnbud Limited, a financial services consulting firm. His prior career included senior roles in investment banking at Smith New Court and NatWest. He holds an MBA from LBS, M Litt from Oxford and a PhD from Cambridge.